
Key points
- One month of tracking gives you real numbers to budget with.
- Record everything, including small purchases and automatic payments.
- Don’t try to change your spending while tracking. Just watch.
- At the end, sort, total and look for surprises.
Why tracking your spending helps
You can probably name your rent and your phone bill. But what do you spend on groceries in a month? Fuel? Takeaway? Many people don’t really know, and it’s easy to guess low.
Tracking your spending for one month swaps guesses for facts. That’s the foundation of a budget that actually fits your life. It usually turns up a few “leaks” as well: small, regular costs that add up to more than you’d think.
Choose a method you’ll stick with
You don’t need any special tool. Pick whatever you’re most likely to use every single day.
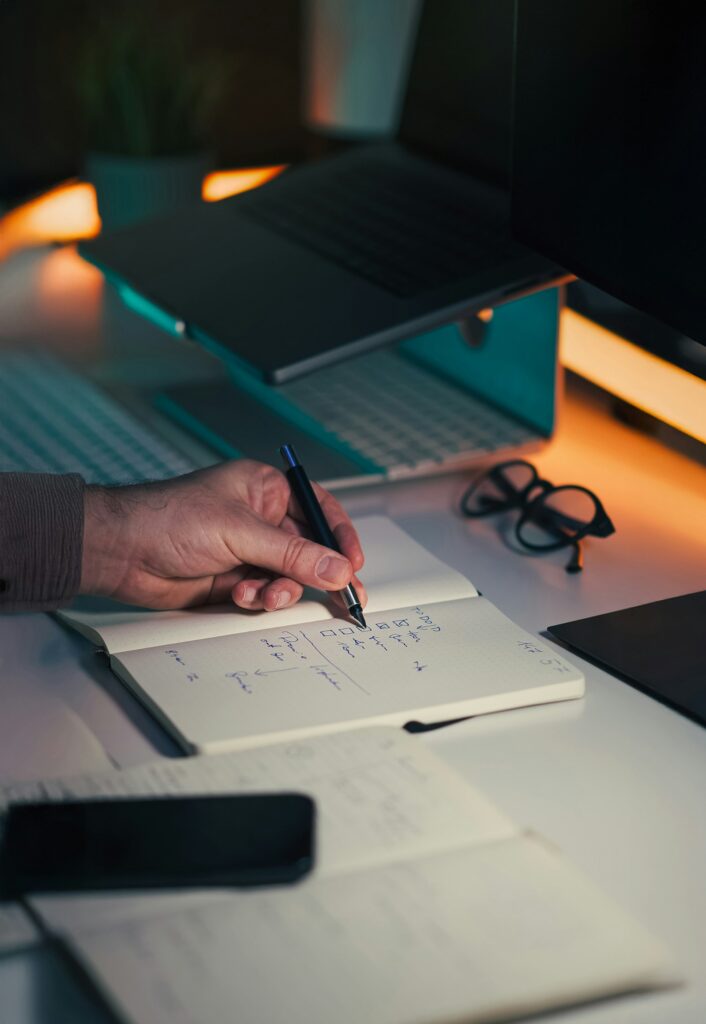
A notebook or a notes file works fine. Write each purchase down as it happens. A spreadsheet is good too, with a column each for the date, the amount, what it was and a category. Or wait until the end of the month, download your bank and card statements and sort the transactions then. That catches card spending well, though it can miss cash. Plenty of people mix it up, using statements for card spending and a quick note for cash.
Recording as you go makes some people more aware of every dollar. Others would rather do a weekly catch-up from their statements. Go with whatever you’ll actually keep doing.
What to record
For each item, note the date, the amount, where or what it was, and a category.
And record everything. Write it down. All of it:
- Card and cash purchases
- Direct debits and automatic payments
- Subscriptions billed to cards
- Bank fees and interest charges
- Transfers to other people for shared costs
If you share money with a partner or housemates, decide up front whether you’re tracking your own spending or the whole household’s. Either works. Just be consistent.
Keep categories simple
Too many categories turn tracking into a chore. A short list is usually plenty: housing and utilities, groceries, transport, eating out and takeaway, health, subscriptions, debt payments, personal and household, fun and entertainment, and other.
If one category turns out to be huge, you can split it later.
Don’t change anything yet
This is the hard part. Once you start tracking, you’ll probably want to cut back straight away. Resist it, just for this month.
You’re after an honest picture of your normal spending. Change your habits halfway through and the numbers won’t reflect real life. Then the budget you build from them may be too tight to keep.
At the end of the month
Add up each category. Then ask yourself a few questions.
What surprised you? Many people find at least one category is bigger than they guessed. What’s regular? Some costs come round every month, while others, like car repairs, may be one-offs. What did you enjoy? Spending that brought you real value may well be worth keeping. And what wouldn’t you miss? Forgotten subscriptions tend to show up here.
How small amounts add up
Say you buy a $6 coffee five workdays a week. That’s $30 a week. Over a year, $30 × 52 = $1,560, which averages $130 a month.
Or say you buy a $14 lunch three times a week. That’s $14 × 3 × 52 ÷ 12 = $182 a month on average.
Neither of these is a problem by itself. They’re just worth knowing about, so that keeping them or changing them is your choice. The same maths works in any currency.
Turning tracking into a budget
Your month of tracking gives you a starting point for every budget category. From there:
- Use your actual totals as the first draft of your budget.
- Add irregular costs that didn’t show up this month, such as annual insurance or gifts. Sinking funds can help with these.
- Compare the total with your take-home pay.
- Adjust the categories where you’d like to spend less, or more.
If what you spent is more than what you earn, that’s useful to know, not a reason to panic. Look first at the categories with the most room to move. If your minimum debt payments alone are more than you can cover, free debt help is available and confidential.
Some people keep tracking every month. Others do a one-month check-in once or twice a year. Either can work.
Common questions
How do you track your spending?
Pick a method you’ll use every day, like a notebook, a spreadsheet or your statements. For everything you spend, record the date, the amount, what it was and a category.
Should I change my spending while tracking?
Try not to for the first month. You want an honest picture of your normal spending, so the budget you build from it fits real life.
How long should you track your spending?
One month gives you real numbers to budget with. Some people keep tracking every month, while others track for a month once or twice a year.
Try it
Put your monthly totals into our budget calculator to see how your spending lines up with your income.
General information only, not financial advice. Your situation is your own.
Budget calculator
Read next
 Money basicsWorking out your real take-home payYour salary isn't what you budget with. Learn how to find your real take-home pay and convert weekly or fortnightly pay into a monthly figure.Starting out4 min read
 Money basicsHow to read your bank statementBank statements can look confusing, but they follow the same pattern everywhere. Learn the key parts, what the codes mean and what to check each month.Starting out5 min read
 Money basicsSetting money goals that stickVague money goals fade fast. Learn how to make goals specific, break them into monthly or per-pay amounts, and keep going when life gets in the way.Starting out5 min read